

Credit Sesame: Grow your score
4.7

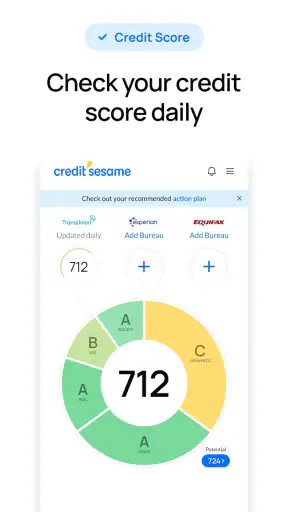
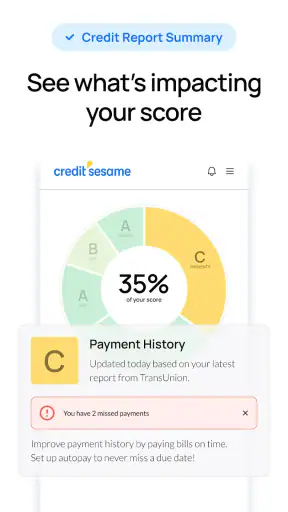
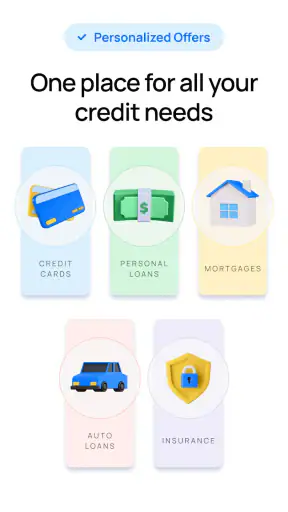
Managing credit from a phone sounds simple until you need an update at an inconvenient moment: before applying for an apartment, checking a card account, or figuring out why a score changed. I spent time with Credit Sesame to see whether it actually makes those moments easier, rather than merely placing financial information on a smaller screen. My overall impression is that it works best as a monitoring companion: useful for keeping an eye on your credit picture, helpful when alerts matter, and less suitable as a complete replacement for a bank app, a credit bureau account, or careful personal budgeting.
This is a free finance app from Credit Sesame, Inc., aimed at people who want to follow their credit progress and organize related information in one place. Its audience is broad, with an Everyone age rating, but the practical value depends on how regularly you check financial information and how comfortable you are reviewing sensitive details through a connected mobile service. I would recommend it to someone building better credit habits, especially if they tend to forget to check important changes. I would be more cautious with anyone expecting instant answers, complete control over every account, or a fully offline experience.
How Credit Sesame feels when your connection matters
When my connection matters, I treat a fresh screen as a useful checkpoint rather than a guarantee that every account has updated. I’ll cover how I separate a temporary loading problem from a financial issue, and why keeping a direct route to the relevant bank or creditor makes the next step clearer.
The first useful moment is usually a connected one
The app’s main appeal appears when it can reach current financial information and present it in a readable way. That makes a stable connection part of the experience, not just a background convenience. When I opened it with a clear purpose, such as checking whether a recent payment or account change had been reflected, the value came from seeing refreshed information rather than from browsing a static dashboard.
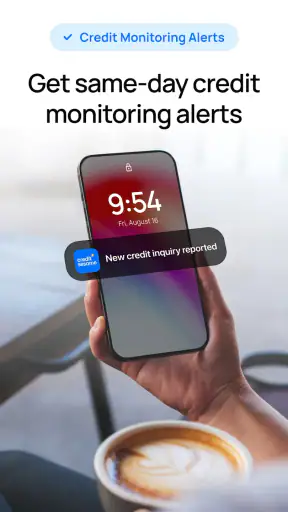
That also changes how I think about the app’s alerts. An alert is most useful when it arrives early enough to prompt a sensible response, but the phone still needs to receive and display it properly. A delayed connection, restricted background activity, or a quick glance while traveling can turn a potentially helpful warning into something I notice later. I would treat notifications as prompts to investigate, not as proof that every detail is already current.
For that reason, I would not use this app as my only source of truth during a time-sensitive financial decision. If I were about to submit a loan application, I would still check the lender’s own information and review the relevant account directly. Credit Sesame is better at helping me notice what deserves attention than at replacing the institutions that actually make lending or account decisions.
A phone-friendly workflow, with limits
On mobile, the strongest workflow is short and purposeful. I can imagine opening the app during a commute, before a conversation with a lender, or after receiving an unexpected notice. The screen is more useful when I already know what I want to check: a score movement, a warning, or a broader view of my credit situation. It is less convincing as something I would leave open for long periods while trying to understand every part of my finances at once.
The small-screen format encourages quick checks, which is both a strength and a weakness. It reduces the effort required to look at credit information, but it can also encourage a shallow reaction to a number that needs context. A score changing is not automatically good or bad in isolation. I would use the app to identify a question, then slow down and verify the underlying account, payment history, or report detail before making a major decision.
One practical habit makes the experience more useful: check after a meaningful financial event rather than repeatedly refreshing out of anxiety. For example, after paying down a card, I would record when the payment was made, allow time for the relevant account cycle, and then use the app as one checkpoint. That avoids treating a mobile display as a live meter that must change immediately.
What happens when the app cannot complete a check
Connected financial apps can fail at several points. The phone may have weak service, the session may need attention, or the information being requested may not be ready to refresh. When that happens, the best response is not to keep tapping the same control. I would first confirm that other internet-dependent apps work, then reopen the app, and finally return later if the problem appears tied to the financial source rather than my phone.
This matters because repeated attempts can create confusion. A screen that has not refreshed should not be interpreted as evidence that nothing changed. Likewise, an old-looking value should not be used to reassure yourself that an account is safe. If an alert concerns possible fraud, an unfamiliar account, or a payment issue, I would contact the relevant bank or creditor directly instead of waiting for Credit Sesame to become available.
Recovery is easier when I keep a simple record of what I expected to see. If I paid a balance, disputed an item, or changed an account, noting the date and the institution involved gives me something concrete to compare later. This is a small but important distinction: the app can support my monitoring routine, while my own notes and direct account access remain the backup when connectivity or timing gets in the way.
Using it without handing over more attention than necessary
Credit information is sensitive, so I would approach the app with the same care I use for banking tools. I would install it only from the official app marketplace, use a strong device lock, and avoid reviewing personal financial details on an unsecured public connection. I would also read each connection or account-linking screen carefully instead of approving everything automatically. The goal is not to avoid useful services; it is to understand what I am choosing before I continue.
A data-conscious routine also means limiting unnecessary checking. Frequent score watching can become stressful, especially for someone who interprets every movement as a crisis. I prefer using the app at planned intervals and responding to meaningful alerts. That approach keeps the service in a supporting role and reduces the temptation to make a financial decision based on a single mobile snapshot.
I would be particularly careful on a shared or borrowed phone. Signing out when appropriate, avoiding saved credentials on devices other people use, and checking that notifications do not reveal more than I want visible on a lock screen are sensible precautions. These are not reasons to dismiss the app, but they are part of using a finance product responsibly. Convenience should not remove basic control over who can see financial information.
Useful situations beyond a quick score glance
The most valuable use case for me is building a review loop. I would open the app, note the current picture, identify any alert or unusual change, and then verify the relevant detail through the original creditor or account provider. After that, I would decide on one action: make a payment, investigate an unfamiliar item, reduce new applications, or simply wait for the next reporting cycle. This turns the app from a passive score display into a prompt for better habits.
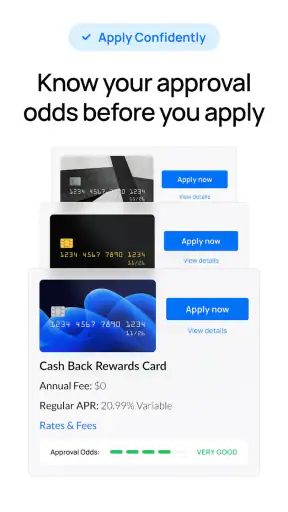
Another useful situation is preparing for a major financial conversation. Before speaking with a landlord, lender, or card issuer, I could use the app to remind myself of questions I need answered. I would not present its view as a guaranteed approval forecast, because lenders use their own criteria. Instead, I would use it to avoid walking into the conversation unaware of recent changes or possible issues.
It can also help someone who is just beginning to pay attention to credit. The low price barrier matters here: the app is free, so a curious user can try a monitoring routine without first committing money. Still, free access does not make every recommendation automatically suitable. I would treat any suggested product or action as something to evaluate against my own goals, existing accounts, and total cost.
Where it sits beside the usual alternatives
I see Credit Sesame as occupying the space between a bank’s account-management app and a formal credit-reporting service. A bank app is usually the better place to confirm a transaction, make a payment, or inspect the account that caused a change. A bureau or lender portal may be the better place to review official report information or complete an application. Credit Sesame is more convenient when I want a broader monitoring view without jumping between several financial institutions.
The trade-off is depth and authority. A single monitoring app can make the overall picture easier to follow, but it cannot become the final decision-maker for every credit question. If I needed detailed documentation for a dispute or a lender requested a particular report, I would go to the appropriate official source. If I only wanted to manage spending and upcoming bills, a budgeting app or my bank’s own tool might fit better.
Its public reception suggests strong interest: the app holds a 4.7 average from around 196 thousand ratings, with over 30 thousand written reviews and more than 5 million installs. Those figures tell me that many people find the basic concept worthwhile, but they do not remove the need to judge the workflow personally. A high average cannot guarantee that the app will match my preferred level of detail, notification style, or tolerance for connected financial services.
Version, access, and who should think twice
The current release is version 7.30.1, and the app requires a device running operating system version 10 or newer. That is worth checking before planning to use it on an older phone. A finance app that cannot be installed or maintained on a particular device is not useful, no matter how appealing its monitoring approach may be.
The product has been available since June 28, 2012, which gives it a long presence in the mobile finance space. I would still judge it by the current experience rather than by its age. Financial interfaces change, connected services can behave differently over time, and my own needs may be more demanding now than when I first started checking credit.
I would skip it if I wanted a completely self-contained tool with no network-dependent checks, or if I disliked the idea of reviewing personal financial information through a third-party service. I would also look elsewhere if my priority were detailed budgeting, investment tracking, or direct bill payment. Those jobs call for different tools, while this app is most focused on credit awareness and monitoring.
My connectivity verdict
After using it as a mobile credit companion, I think Credit Sesame succeeds when I treat connectivity as part of the workflow rather than an invisible guarantee. Its convenience comes from bringing credit-related monitoring into a place I already carry, but that convenience works best when I verify important details and keep a backup route through my bank, creditor, or official reporting source.
My recommendation is to use it as an early-warning and habit-building tool, not as the sole authority for a major financial decision. It is a good fit for someone who wants a free way to pay closer attention to credit, receive useful prompts, and gather questions before taking action. It is a weaker fit for someone seeking comprehensive money management or certainty without checking the original source.
In everyday terms, I would keep it for scheduled check-ins, investigate alerts promptly, avoid overreacting to one number, and use a reliable connection when reviewing sensitive information. That combination gives the app a clear role: it helps me notice and organize what deserves attention, while the final verification and decision remain in my hands.
4.7
32.07K Reviews
Pros
- Free credit score updates help track changes over time.
- Credit monitoring can alert you to potential identity theft.
- Personalized recommendations make credit goals easier to follow.
- Budget and debt insights can support better financial decisions.
- Simple interface makes credit information easy for beginners to understand.
Cons
- Some features and offers are limited unless you use partner services.
- Frequent financial product promotions may feel distracting.
- Credit score information may differ from scores used by lenders.
- Advanced credit-building tools can involve fees or eligibility requirements.
- App features and offers may vary depending on your location and profile.


